Autonomous on the Move: How AI-Driven Robotics Are Rebuilding America's Warehouse Infrastructure
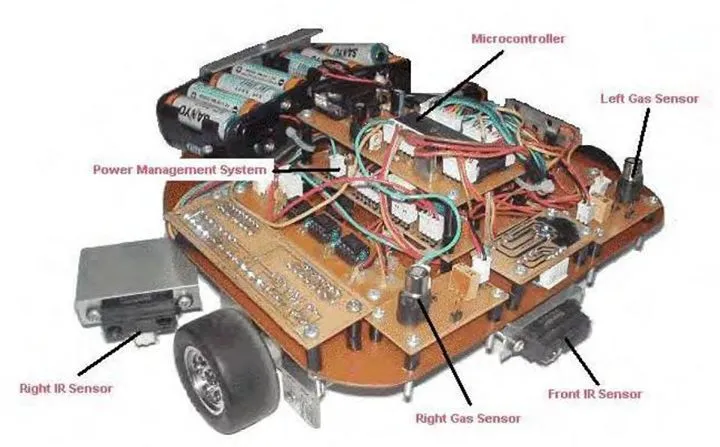
Photo: Emmgon at English Wikipedia, CC BY-SA 3.0, via Wikimedia Commons
The American supply chain has never fully recovered its composure. Between pandemic-era disruptions, a structural labor shortage that predates COVID-19, and surging consumer expectations driven by next-day delivery norms, the logistics sector finds itself under extraordinary pressure. The solution, increasingly, is not hiring more workers — it is deploying smarter machines.
Across the country, warehouses and distribution centers are integrating autonomous mobile robots (AMRs) and AI-driven orchestration platforms at a pace that would have seemed improbable a decade ago. The transformation is not merely technological. It is operational, economic, and, for many workers, deeply personal.
The Scale of the Problem
The US Bureau of Labor Statistics has consistently flagged warehousing and transportation as sectors with some of the highest turnover rates in the American economy — often exceeding 40 percent annually. Physical demands, repetitive tasks, and shift-work schedules make sustained staffing a chronic challenge for distribution center operators.
Simultaneously, e-commerce growth has placed extraordinary throughput demands on facilities that were, in many cases, designed for an earlier era of retail logistics. The result is a system straining at its seams: delayed shipments, elevated error rates, and cost overruns that erode margins across the supply chain.
It is within this context that autonomous robotics has moved from a speculative investment to a strategic necessity.
AMRs in Action: Case Studies from the Floor
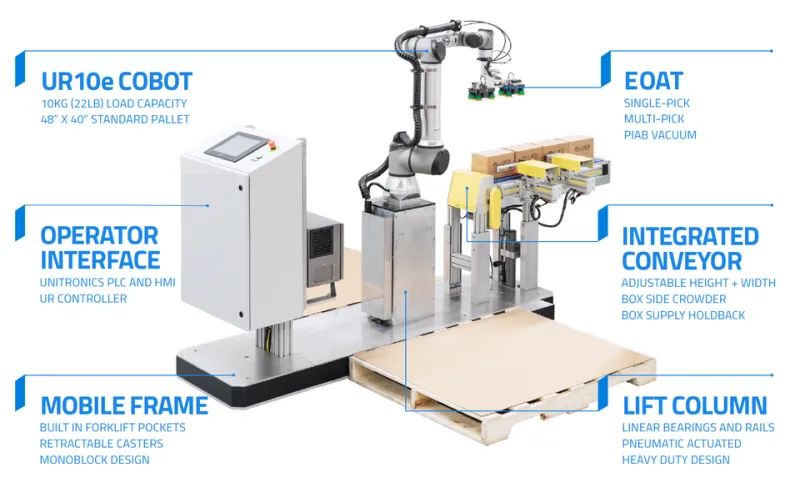
In the greater Columbus, Ohio area — a logistics hub that serves a significant portion of the US Midwest — several major third-party logistics (3PL) providers have deployed AMR fleets from vendors including Locus Robotics, 6 River Systems, and Fetch Robotics (now part of Zebra Technologies). These platforms enable robots to navigate dynamically alongside human workers, handling goods movement while staff focus on tasks requiring dexterity and judgment.
One operations director at a regional fulfillment center, speaking on background, described a 34 percent reduction in picking errors following AMR deployment and a measurable decrease in worker fatigue-related incidents. "The robots don't replace our people," she noted. "They absorb the physical monotony so our team can stay sharp on the decisions that actually matter."
Further south, in a temperature-controlled distribution facility outside Atlanta, a grocery retailer integrated AI-powered sortation robots capable of processing thousands of individual SKUs per hour. The system uses computer vision and machine learning to identify, sort, and route products in real time — a task that previously required large teams working in physically demanding cold-storage conditions.
The Intelligence Layer: AI as the Nervous System
Hardware alone does not explain the leap in capability. The real differentiator in modern warehouse robotics is the AI layer that coordinates robot behavior, optimizes routing, predicts inventory demand, and integrates with enterprise resource planning (ERP) systems.
Platforms such as Symbotic and GreyOrange deploy AI orchestration engines that treat an entire warehouse as a unified system rather than a collection of discrete processes. These systems ingest data from sensors, conveyors, order management software, and external logistics feeds to make real-time decisions about task prioritization and resource allocation.
Dr. Marcus Ellery, a supply chain systems researcher at Georgia Tech, describes this convergence as the critical inflection point. "We are past the era of isolated automation," he explained in a recent industry panel. "The competitive advantage now belongs to operators who can integrate robotic hardware with intelligent software that learns and adapts at scale."
Labor Displacement or Labor Evolution?
The question that shadows every conversation about warehouse robotics is its impact on the American workforce. The answer, as with most technological transitions, resists easy categorization.
Some roles — particularly those involving repetitive horizontal transport of goods — are being significantly reduced. However, facilities that have undergone substantial automation frequently report a shift in the composition of their workforce rather than a wholesale reduction. Demand rises for robot fleet technicians, systems integrators, and data analysts capable of interpreting operational dashboards.
The Warehouse Education and Research Council (WERC) has documented growing investment by logistics companies in upskilling programs, often developed in partnership with community colleges and technical institutes. These initiatives aim to transition workers from floor-level picking roles into technology-adjacent positions, though the pace and scale of such programs remains inconsistent across the industry.
What is clear is that the facilities that fail to automate face a different kind of workforce problem: an inability to attract and retain staff at all.
Infrastructure Challenges and the Road Ahead
Deployment is not without friction. Legacy warehouse infrastructure — narrow aisles, inconsistent flooring, outdated Wi-Fi coverage — can complicate AMR integration significantly. Many operators are discovering that the capital expenditure for robotics must be accompanied by parallel investment in facility upgrades and connectivity infrastructure.
Edge computing is emerging as a partial solution, enabling real-time processing of sensor data without dependence on cloud latency. Companies including NVIDIA and Intel are actively developing embedded compute platforms tailored for warehouse robotics environments.
Looking ahead, the next frontier is full-stack autonomy: systems capable of unloading inbound trailers, putting away stock, fulfilling orders, and loading outbound shipments with minimal human intervention. Startups such as Dexterity and Machina Labs are developing robotic manipulation systems designed to handle the irregular, unpredictable nature of inbound freight — long considered one of the final barriers to end-to-end warehouse automation.
The Competitive Imperative
For US logistics operators, the window for deliberate, unhurried evaluation of autonomous robotics is narrowing. Early adopters have established operational advantages in throughput capacity, error rates, and cost per unit that are increasingly difficult for laggards to close.
The supply chain crisis that defined the early 2020s was, in retrospect, a forcing function — an event that compressed years of automation adoption into a compressed timeline. The companies that responded with investment rather than hesitation are now operating with a structural advantage that compounds over time.
America's supply chain future will be built not on additional labor alone, but on the intelligent integration of human expertise and autonomous capability. The robots are already on the floor. The question now is how well operators can put them to work.